RESPA MSA Compliance: What Mortgage Teams Must Get Right
Marketing services agreements are not banned under RESPA, but plenty of them violate it anyway. The Consumer Financial Protection Bureau has made clear that an MSA survives scrutiny only when it covers actual, necessary, and distinct marketing services, and when payment is tied to fair market value rather than referral volume. Get that structure wrong, and even a well-drafted contract can trigger RESPA Section 8 liability.
TL;DR:
- Payments must be based on the fair market value of actual marketing services, not referral volume or business generated.
- Having a written scope of work, verified performance, and independent valuation are essential to defend an MSA against RESPA violations.
- Payments made before verifying that marketing work was performed are the most common cause of enforcement issues.
- Proper documentation should include campaign records, invoices, timelines, and performance metrics, ideally captured automatically.
- A well-structured, verifiable MSA minimizes risk, while sloppy operations and poor record-keeping increase exposure to RESPA liability.
Table of Contents
- What RESPA Section 8 and Regulation X Actually Require
- What Marketing Services Agreements Are Under CFPB Guidance
- When Does an MSA Violate RESPA?
- A Compliance Checklist for Drafting and Running an MSA
- How to Document and Value Marketing Services
- A Compliant MSA vs. a Noncompliant One
- Why Documentation Discipline Beats Legal Theory
- Turn Your Marketing Records Into Compliance Evidence
- Sources
What RESPA Section 8 and Regulation X Actually Require
RESPA compliance guidelines start with one statute: 12 U.S.C. § 2607. Section 8(a) bars anyone from giving or accepting a fee, kickback, or thing of value under any agreement to refer settlement service business. It doesn’t matter whether the payment is called a referral fee, a co-marketing fee, or a sponsorship. If the substance is “pay me and you get the business,” it’s illegal.
Regulation X, specifically 12 CFR § 1024.14, restates that prohibition in more operational language. It defines “thing of value” broadly (cash, discounts, free services, credit, anything with monetary worth) and carves out an exception in §1024.14(g) for payments that compensate for goods or services actually furnished.
The penalties are not theoretical:
- Civil liability can reach three times the amount of the illegal charge.
- Statutory fines can run up to $10,000 per violation.
- Criminal exposure can include potential imprisonment.
- The CFPB has shown it will pursue enforcement even against parties who believed their MSA was defensible.
That last point matters most for mortgage compliance teams. The agency doesn’t grade on intent. It grades on facts.
What Marketing Services Agreements Are Under CFPB Guidance
A marketing service agreement, in CFPB terms, is a contract where one party (often a lender) pays another party (often a real estate agent, builder, or vendor) for defined marketing work, such as co-branded advertising, lead generation campaigns, or event sponsorships, explained in detail in advertising partnerships with real estate agents. The tension with RESPA co-marketing rules arises because the paying party in many MSAs also happens to be a source of referrals.
The regulatory history here matters. In October 2015, the CFPB issued a bulletin warning heavily against MSAs, and the mortgage industry largely read it as a near-ban. That changed on October 7, 2020, when the CFPB formally rescinded the 2015 bulletin and issued FAQs clarifying its actual position.
The 2020 FAQs established three practical points:
- MSAs are not per se illegal under RESPA.
- Structure and real-world implementation both matter. A pristine contract paired with sloppy execution still creates exposure.
- Payment must be reasonably related to fair market value of the marketing services delivered, not the value of the business referred.
The CFPB explicitly said it looks at the course of conduct, meaning what actually happened month to month, not just what the contract says on paper.
When Does an MSA Violate RESPA?
The dividing line between a lawful MSA and a RESPA violation comes down to a facts-and-circumstances test, not a checkbox. Regulators and courts look at whether the marketing services were real, whether the price matches the market, and whether payment timing lines up with performance rather than referral volume.
Red flags that draw enforcement attention:
- Payments that scale with the volume of referrals sent, rather than the marketing work performed.
- Fees that exceed independently verified fair market value for comparable services.
- Marketing “services” that are nominal, duplicative, or never actually delivered.
- Payment made in advance of any verification that work occurred.
Green flags that support a defensible MSA:
- A written scope of work with specific, measurable marketing deliverables.
- Independent valuation or market benchmarking behind the negotiated price.
- Payment released only after performance is verified against agreed metrics.
- Clear separation between marketing functions and any referral-generating activity.
One rule cuts across every scenario: under §1024.14(g)(2), the value of referred business can never be used to justify a payment amount, even if the marketing itself was real.
Pro Tip:If you can’t explain, in one sentence, what specific marketing deliverable justified a specific dollar amount, an examiner won’t be able to either, and that gap is where enforcement actions start.
A Compliance Checklist for Drafting and Running an MSA
Most MSA legal requirements fail not because the concept is illegal, but because the paperwork and operations don’t match the CFPB’s expectations. A working compliance checklist covers three layers.
Contract terms:
- Written, specific scope of marketing tasks (not vague “promotional support”).
- Defined, measurable deliverables tied to each payment.
- Payment timing gated on verified performance, not calendar dates.
- Indemnity clauses and audit rights for both parties.
Operational controls:
- Documentation created before payment, not reconstructed afterward.
- Independent valuation or market-rate benchmarking on file.
- A hard line separating marketing functions from referral relationships.
Governance:
- Staff training on what counts as a “thing of value” under Regulation X.
- Retention policies for campaign evidence, ideally several years given RESPA’s statute of limitations exposure.
- Periodic internal audits and a defined trigger for counsel sign-off before renewing or amending any MSA.
Nearly every enforcement matter traces back to one failure: a payment made before performance was verified. Fix that single sequencing problem, and most other risks shrink with it.
How to Document and Value Marketing Services
Best practices for RESPA compliance come down to proof. Three valuation methods hold up under review: market comparables (what similar marketing services cost elsewhere), cost-plus calculations for work done in-house, and third-party appraisals for unique or specialized campaigns. Each requires a written rationale explaining why that method fit the situation, according to valuation methodology used in RESPA-related partnership reviews.
Keep these records on file for every campaign:
- Campaign briefs and creative assets.
- Media buy receipts and vendor invoices.
- Timelines showing when work started and finished.
- Performance metrics and attribution reports.
- Staff timesheets for in-house marketing labor.
An auditable CRM that timestamps campaign activity and attribution automatically builds this evidence trail as a byproduct of normal work, rather than as a scramble after an examiner’s letter arrives.
Pro Tip:Contemporaneous beats retroactive every time. A campaign log built the week the work happened carries far more weight than a reconstructed summary written after a subpoena.
A Compliant MSA vs. a Noncompliant One
The failed version: A lender pays a real estate agent $1,500 a month for “co-marketing.” The agent occasionally reposts the lender’s listings but keeps no records, and the payments track almost exactly with how many buyers the agent sends the lender’s way. No invoices, no campaign brief, no independent valuation. This is a textbook RESPA violation.
The compliant version: A lender pays a marketing vendor for a defined quarterly campaign, digital ads, print materials, event sponsorship, with a signed scope of work, an independent market-rate quote, and payment released only after the vendor submits performance metrics and invoices.
The difference isn’t the existence of a payment. It’s documentation, valuation, and timing.
Why Documentation Discipline Beats Legal Theory
Most mortgage teams treat MSA compliance as a drafting exercise, get the contract language right and move on. That’s backwards. Examiners care far more about what actually happened than what the contract says should happen, which means the highest-leverage compliance work is operational, not legal. Prioritize MSAs with measurable deliverables and independent valuation baked in from day one, and build systems that capture evidence automatically rather than relying on someone to remember to file an invoice. Review Loan Officer AI’s compliance resources before your next MSA renewal, not after an inquiry letter shows up.
— Jared Hart
Turn Your Marketing Records Into Compliance Evidence
Loan Officer AI gives mortgage teams something a manual spreadsheet never will: a timestamped, campaign-by-campaign record of what marketing activity actually happened and when, built automatically instead of reconstructed under deadline pressure.
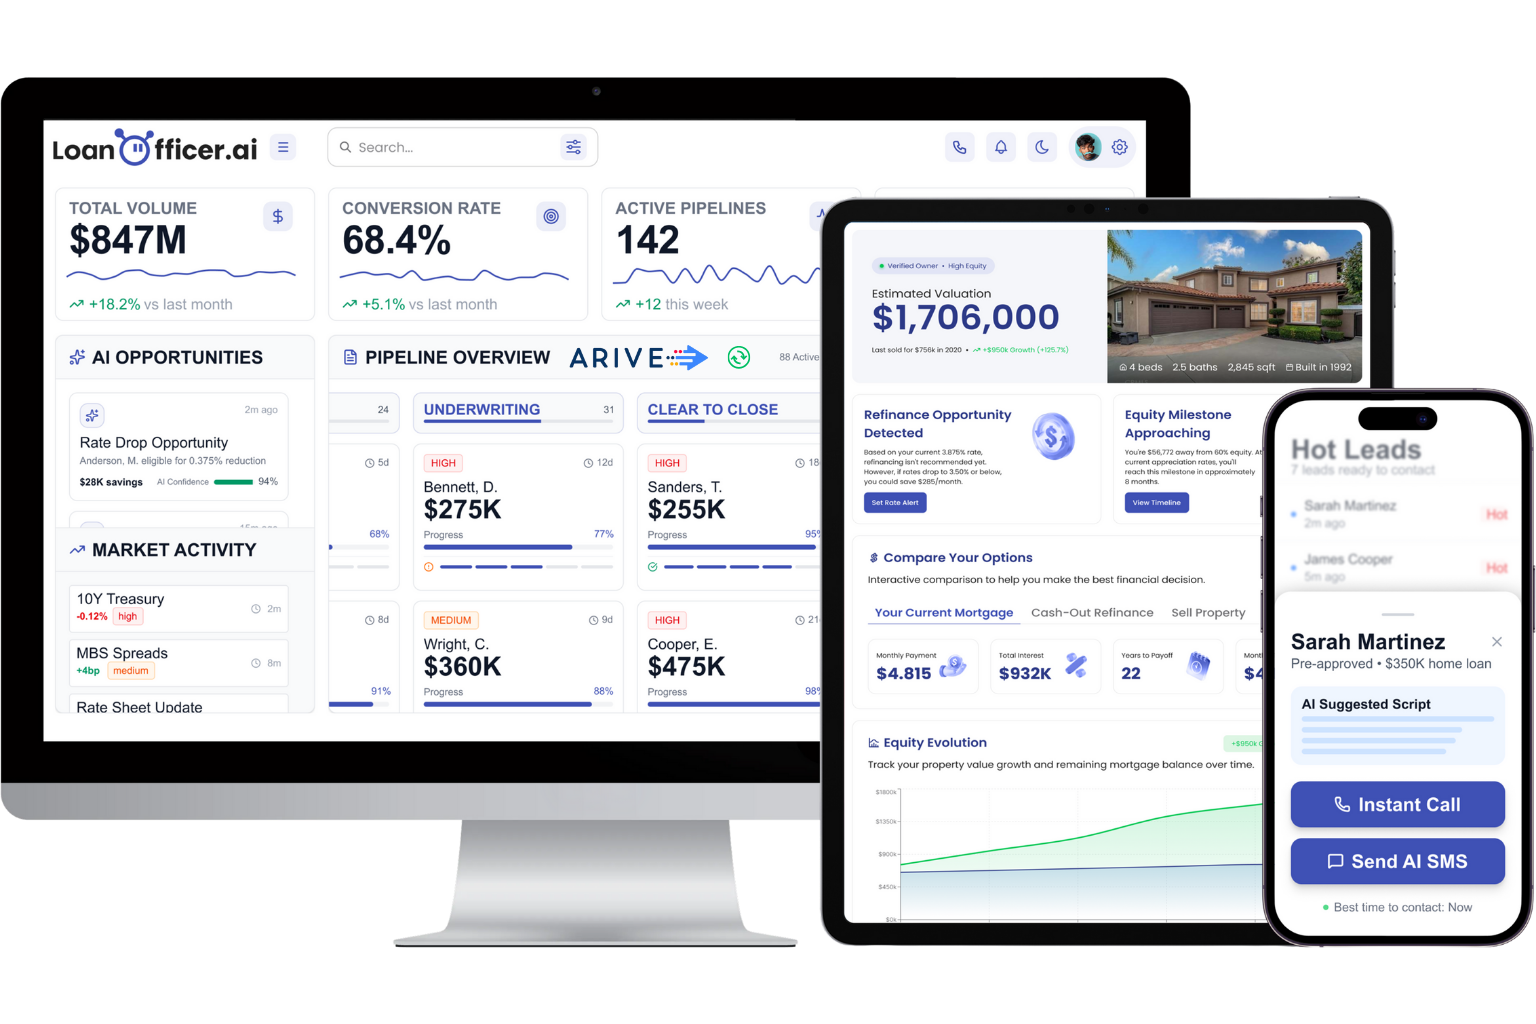
The platform logs campaign activity, attribution data, and borrower engagement as it happens, which means the documentation examiners ask for during an MSA review already exists instead of getting assembled after the fact. Pipeline attribution and LOS integrations tie marketing spend to actual outcomes, giving compliance teams the kind of contemporaneous evidence that valuation reviews depend on. For teams juggling multiple realtor partnerships and vendor relationships at once, that audit trail is the difference between a quick file review and a drawn-out inquiry. Start a trial of the mortgage CRM built for loan officers who’d rather document once than defend twice.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
Sources
- 12 USC § 2607: Prohibition against kickbacks and unearned fees
- § 1024.14 Prohibition against kickbacks and unearned fees. | Consumer Financial Protection Bureau
- CFPB provides clearer rules of the road for RESPA marketing service agreements