PhoneBurner Alternatives for Mortgage Pros: 2026 Shortlist
For mortgage loan officers, the best PhoneBurner alternatives are Loan Officer AI (mortgage-first AI CRM with smart dialer), BNTouch (LOS-integrated CRM), Surefire (marketing automation), Mojo Dialer (high-volume dialing), and Kixie (AI-enhanced power dialer). Loan Officer AI is the strongest single replacement because it combines native LOS sync, AI follow-up, and realtor co-marketing in one platform built specifically for loan pipelines.
- AI-CRM hybrid (Loan Officer AI): Automated follow-up, refinance opportunity detection, realtor co-branded campaigns, and a smart dialer in one mortgage-native platform — no middleware required.
- LOS-integrated CRM (BNTouch, Surefire): Deep LOS connections and templated marketing campaigns; better for teams already embedded in specific LOS ecosystems but lighter on AI automation.
- Dialer-first platform (Mojo Dialer, Kixie): High call volume and parallel dialing; strongest for pure outbound throughput, but LOS integration often requires middleware and co-marketing features are limited.
Quick next step: Request a demo of Loan Officer AI. It’s the only option on this list built exclusively for mortgage professionals, with a partner retention rate that stands out in the industry.
Table of Contents
- How the top PhoneBurner alternatives compare for mortgage professionals
- How to choose the right PhoneBurner alternative for your mortgage business
- What implementation looks like: timeline, costs, and migration tips
- Why AI-powered, mortgage-focused CRMs beat generic dialers for loan officers
- Final recommendation: the best PhoneBurner alternative for mortgage professionals
- Key takeaways
- What loan officers actually get wrong when switching CRM platforms
- Loan Officer AI is the mortgage-first replacement your pipeline needs
- Sources and further reading
How the top PhoneBurner alternatives compare for mortgage professionals
The mortgage CRM market splits into three categories: LOS-integrated platforms, purpose-built mortgage CRMs, and broader dialer/marketing platforms. Each serves a different primary need.
| Feature dimension | Dialer-first platforms | LOS-integrated CRMs | AI-CRM hybrid (Loan Officer AI) |
|---|---|---|---|
| Dialer type | Predictive/parallel (high volume) | Power dialer (moderate volume) | Smart dialer with AI routing |
| AI automation | Minimal or add-on | Basic drip sequences | AI follow-up, opportunity detection, lead scoring |
| Realtor/partner co-marketing | Not included | Templated campaigns | Native co-branded campaigns with attribution |
| LOS integrations | Middleware (Zapier/webhooks) | Native (Encompass, Calyx) | Native (Encompass, Calyx, others) |
| Mortgage pipeline management | Generic stages | Mortgage-specific stages | Purchase + refinance stage logic |
| Pricing model | Per-seat + dialer minutes | Per-seat, tiered | Flat/subscription, optional onboarding fee |
| Compliance & security | Basic DNC scrubbing | TCPA controls, some SOC2 | TCPA/DNC controls, SOC2 statements |
| Migration ease | Moderate (CSV import) | Moderate to complex | Guided onboarding with data mapping |
| Mobile app | Yes | Yes | Yes |
| Reporting & analytics | Call volume, connect rates | Pipeline and marketing reports | Pipeline, referral attribution, AI insights |
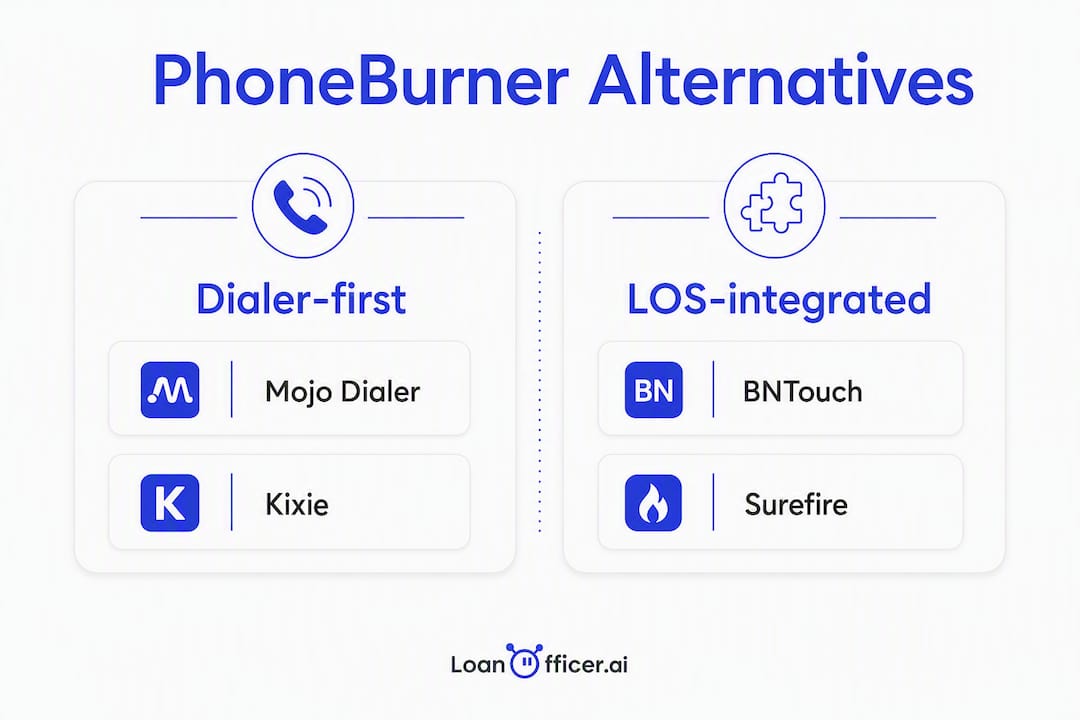
Dialer-first platforms (Mojo Dialer, Kixie) win on raw call volume. Kixie’s AI-enhanced power dialer handles spam-flag mitigation and parallel lines well. The gap shows up in co-marketing: neither platform offers realtor-attributed campaigns out of the box, and LOS milestone sync typically requires custom middleware that can drop updates during critical loan stages.
LOS-integrated CRMs (BNTouch, Surefire) have the deepest native connections to Encompass and Calyx. Surefire’s templated content library is strong for compliance-reviewed marketing. The trade-off is AI depth — automated opportunity detection and intelligent follow-up sequencing are limited compared to a purpose-built AI platform.
Loan Officer AI covers all three dimensions natively. For partner-driven loan officers who get 60% or more of production from real estate referrals, the co-marketing attribution alone justifies the switch.
How to choose the right PhoneBurner alternative for your mortgage business
Prioritize LOS integration, speed-to-lead dialing, realtor co-marketing, TCPA/DNC controls, and AI follow-up that understands loan workflows — in that order.
Core selection criteria:
- LOS integration quality: Native beats middleware every time. A Zapier-based sync can silently fail when a loan moves from processing to underwriting, leaving your CRM showing stale data.
- Speed-to-lead dialing: Calling a lead within two minutes vastly outperforms waiting ten. Your dialer needs auto-routing and parallel dialing to hit that window consistently.
- Realtor/partner co-marketing: If referrals drive your pipeline, templated co-branded campaigns with attribution tracking are higher ROI than any generic CRM feature.
- TCPA/DNC compliance controls: Express consent workflows and DNC scrubbing must be built in, not bolted on.
- AI follow-up logic: Generic drip sequences don’t understand the difference between a purchase lead at pre-approval and a refinance candidate at rate-watch. Mortgage-aware AI does.
Demo checklist (30–45 minutes):
- Show a live LOS sync — trigger a loan stage change in Encompass or Calyx and confirm the CRM updates in real time.
- Run a speed-to-lead test: how fast does the dialer route an inbound lead to an available LO?
- Send a co-branded realtor campaign and show attribution reporting.
- Walk through the TCPA/DNC scrubbing workflow for a list upload.
- Export a pipeline report and confirm it maps to your actual loan stages.
Red flags to watch:
- Middleware-only LOS connections (Zapier, webhooks with no native API)
- No SOC2 or PCI compliance documentation available on request
- Per-seat pricing with separate dialer-minute charges that balloon at scale
- Vague consent tracking for AI voice or SMS outreach
- No case studies from actual loan officers or mortgage teams
Trust signals that matter: LOS partner badges (Encompass-certified, Calyx-listed), SOC2 Type II statements, demo availability without a sales wall, and published case studies from mortgage professionals.
What implementation looks like: timeline, costs, and migration tips
A typical switch from PhoneBurner to a mortgage CRM takes four to eight weeks from pilot to full rollout, with the LOS integration mapping phase being the most variable.
| Phase | Small team (1–5 LOs) | Branch (multiple LOs) |
|---|---|---|
| Pilot setup | 1–2 weeks | 1–2 weeks |
| LOS integration & data mapping | 2–3 weeks | 3–5 weeks |
| Full rollout & training | 1–2 weeks | 2–4 weeks |
| Total ramp time | 4–6 weeks | 6–8 weeks |
Cost drivers to budget for:
- One-time onboarding fee (common with mortgage-specific platforms; covers data mapping and LOS configuration)
- Per-seat vs. flat/branch pricing — flat-rate models are more predictable for growing teams than per-seat structures that compound as you add LOs
- Dialer minutes or connection fees (common with dialer-first platforms; less common with AI-CRM hybrids)
- Data cleanup costs if your PhoneBurner contact list has duplicates, missing consent flags, or outdated loan stages
Migration checklist:
- Export all contacts from PhoneBurner with full field mapping (name, phone, email, loan status, consent date)
- Map existing loan stages to the new platform’s pipeline structure before import
- Configure TCPA/DNC scrubbing rules before any outbound dialing begins
- Set up realtor co-marketing attribution from day one — retrofitting it later is painful
- Validate LOS sync with a test loan before going live with your full pipeline
Why AI-powered, mortgage-focused CRMs beat generic dialers for loan officers
A mortgage-aware AI platform materially increases contact rates, referral conversion, and pipeline hygiene compared with a generic power dialer. The reason is specificity: loan pipelines have distinct stages, compliance requirements, and relationship dynamics that generic sales tools were never designed to handle.
Speed-to-lead is the single most important KPI in mortgage sales. Hitting contact windows under five minutes — ideally under two — materially increases conversion. Parallel dialing and auto-routing are the proven mechanisms to get there consistently. A generic dialer can hit those numbers on volume; the difference is what happens after the call connects.
Mortgage-specific AI adds three layers a generic dialer cannot replicate. First, LOS milestone sync means your follow-up sequences automatically adjust when a loan moves from application to underwriting — no manual stage updates. Second, AI follow-up automation detects refinance and HELOC opportunities in your existing database by monitoring rate changes and equity thresholds, not just drip-scheduling emails. Third, realtor co-branded campaigns with attribution tracking turn every closed loan into a documented referral data point your partners can see.
Some platforms now bundle voice AI for after-hours intake and missed-call recovery. That helps capture off-hour leads, but voice AI without native LOS integration often requires custom middleware work to be genuinely useful in a mortgage workflow.
Pro Tip:AI voice agents carry real TCPA litigation risk when deployed without express written consent workflows. Relying on lead-aggregator consent language is often insufficient — recent TCPA suits in mortgage have targeted exactly this gap. Before enabling any AI voice feature, have your compliance team review the consent capture flow and DNC scrubbing logic.
Final recommendation: the best PhoneBurner alternative for mortgage professionals
Loan Officer AI is the strongest replacement for mortgage loan officers who need more than a dialer. Native LOS sync with Encompass and Calyx, AI-driven follow-up and opportunity detection, realtor co-marketing with attribution, and a smart dialer in one platform — no middleware, no stitched-together stack.
For teams that must prioritize raw dialer volume above everything else, a dialer-first platform handles throughput well. For teams already locked into a specific LOS ecosystem with heavy compliance review processes, an LOS-integrated CRM may be the lower-friction path. But for most independent loan officers and small teams, the AI automation and partner co-marketing in a mortgage-native platform will outperform a generic dialer within the first 60 days.
Before you commit to any platform:
- Confirm native LOS integration (not middleware) with a live demo test
- Validate TCPA/DNC consent workflows with your compliance officer
- Involve operations and at least one producing LO in the evaluation, not just management
- Run a 30-day pilot measuring speed-to-lead, contact rate, and referral campaign sends before full rollout
Key takeaways
For mortgage loan officers switching off PhoneBurner, the platform that combines native LOS integration, AI follow-up automation, and realtor co-marketing in one mortgage-native tool delivers the strongest pipeline results.
| Point | Details |
|---|---|
| Mortgage-first shortlist | Loan Officer AI, BNTouch, Surefire, Mojo Dialer, and Kixie each serve different primary needs. |
| LOS integration is the top criterion | Native Encompass/Calyx sync beats middleware connections that can silently fail during loan stage updates. |
| Speed-to-lead under two minutes | Sub-2-minute contact windows materially increase conversion; parallel dialing and auto-routing are required to hit them. |
| TCPA/DNC compliance is non-optional | Validate express consent workflows and DNC scrubbing before any AI voice or SMS outreach goes live. |
| Loan Officer AI as the recommended pick | Loan Officer AI covers AI automation, smart dialer, LOS sync, and realtor co-marketing natively, making it the recommended choice for most mortgage professionals. |
What loan officers actually get wrong when switching CRM platforms
Most loan officers evaluate dialing software the way they’d evaluate a phone plan: minutes, price, and whether it connects. That framing misses the real cost of switching.
The platforms that look cheapest at the per-seat level almost always have the most expensive hidden layer: middleware. When your LOS sync runs through Zapier, you’re not just paying for an extra tool — you’re accepting that a Zap failure during underwriting will leave your CRM showing a loan still in processing. That’s not a minor inconvenience. It’s a missed follow-up, a confused realtor partner, and potentially a borrower who feels forgotten at the worst moment in the transaction.
The other thing loan officers consistently underestimate is how much of their pipeline is actually a relationship problem, not a volume problem. More dials won’t fix a referral partner who hasn’t heard from you in 90 days. AI-driven co-marketing automation — the kind that sends a co-branded market update to your top 10 realtor partners without you touching it — does. That’s the gap between a generic dialer and a mortgage-native platform, and it shows up in closed loans, not call logs.
One more thing worth saying plainly: compliance is not a vendor’s problem to solve for you. TCPA exposure from AI voice agents is real and growing. Before you enable any automated calling or voice AI feature on any platform, get your compliance officer in the room. The platforms that make this easy — with built-in consent tracking and DNC scrubbing — are the ones worth paying for.
Loan Officer AI is the mortgage-first replacement your pipeline needs
Switching off PhoneBurner doesn’t have to mean choosing between dialing power and CRM depth. Loan Officer AI gives mortgage professionals both in one platform: a smart dialer with AI-powered follow-up, native LOS sync with Encompass and Calyx, realtor co-branded campaigns with attribution, and refinance opportunity detection built into the pipeline view.

The onboarding is structured around mortgage workflows — not generic sales pipelines — so your loan stages, consent flows, and partner attribution are configured correctly from day one. Pricing is subscription-based with a one-time onboarding fee, which keeps costs predictable as your team grows. Most teams are live within four to seven weeks.
Trial checklist: Test LOS sync with a live loan, run a speed-to-lead measurement on an inbound lead, send one co-branded realtor campaign, verify TCPA/DNC scrubbing on a list upload, and export a pipeline report before you commit.
Start your Loan Officer AI trial and bring your LOS admin, one producing LO, and your compliance contact to the first session.
This article is general information for mortgage professionals evaluating CRM and dialer platforms. It is not legal or compliance advice. Confirm TCPA, DNC, and data-handling requirements with a qualified compliance professional before deploying any automated outreach tool.
Sources and further reading
- Mortgage Dialer Strategies to Close Loans Faster — Predictive vs. power dialer mechanics for mortgage teams
- Best Dialer for Mortgage Brokers: Increase Conversations & Loan Volume — Workflow-focused guide to dialer selection
- Best CRM for Mortgage Loan Officers 2026: Honest Comparison — Category breakdown and co-marketing ROI analysis
- CRM for Mortgage & Loan Officers | Conduyt — Middleware risk and LOS integration depth analysis
- AI Voice Calls Spark TCPA Risk in Mortgage — TCPA litigation risk for AI voice agents in mortgage
- Cold Calling for Mortgage Brokers: Playbook — Speed-to-lead benchmarks and parallel dialing strategy
- Power Dialing for Loan Officers, Mortgage Brokers, and B2B Lenders — Kixie’s dialer positioning for mortgage and B2B lending
- Top Mortgage Financing Alternatives — Industry-adjacent perspective on financing platform alternatives
